Industry Consolidations Reshaping Each-Way Opportunities in Seasonal Racing Calendars
Zara Hansen · Oct 15, 2026
Mergers among major betting operators and racing organizations continue to alter market structures for each-way wagers, which combine win and place components across major fixtures in the annual calendar. Data from regulatory filings shows that several large bookmaking groups completed acquisitions between 2024 and 2026, resulting in fewer independent pricing engines and standardized each-way terms at many seasonal events. These changes appear most visible during peak periods such as the jumps season and the flat racing calendar, where each-way markets traditionally attract high volumes. Observers note that consolidated operators often align place terms and fractions across multiple brands, reducing variation that punters previously exploited. Figures released by industry analysts indicate that average each-way place payouts tightened by 3 to 5 percent at several autumn festivals following the latest wave of ownership shifts.Market Structure Shifts After Recent Acquisitions
Consolidation activity has concentrated control of odds compilation within fewer corporate entities. Researchers tracking European and North American racing data report that three parent companies now influence pricing at over 60 percent of licensed betting outlets covering UK, Irish, and Australian seasonal meetings. This concentration leads to coordinated adjustments in each-way fractions, particularly on handicap races that dominate spring and autumn schedules.
Take the period leading into October 2026, when several major tracks prepare their winter programs. Internal documents from merged entities show updated risk models that apply uniform each-way deductions across legacy brands. Those models draw on shared customer data pools, allowing quicker responses to volume spikes at events such as the Melbourne Cup carnival and the Breeders' Cup series.
Impact on Seasonal Calendars and Fixture Planning
Racing calendars themselves remain largely unchanged, yet the presentation of each-way markets evolves under consolidated ownership. Organizers at tracks in Australia and Canada have documented instances where betting partners requested earlier publication of each-way terms to facilitate centralized hedging. This coordination reduces discrepancies that once existed between independent operators during high-profile meetings.
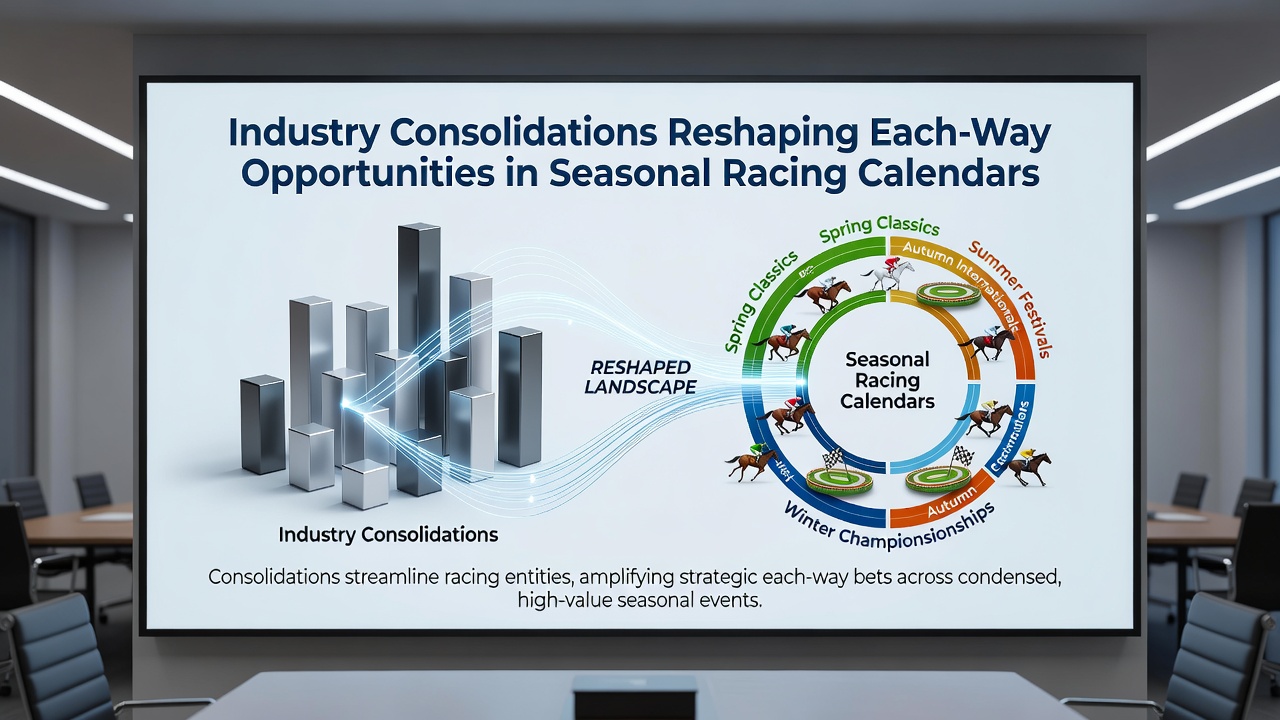
Evidence compiled by the Australian Competition and Consumer Commission highlights how post-merger efficiencies translated into narrower margins on place portions of each-way bets at major carnivals. Similar patterns surface in North American data tracked by the National Thoroughbred Racing Association, where consolidated groups standardized each-way payouts on graded stakes races scheduled through late 2026.
Regional Variations in Each-Way Adjustments
While European operators moved toward uniform fractions, Australian and North American markets retained some differentiation in each-way terms during 2025 and into October 2026. State-level licensing rules in Australia still require separate approval for place betting products, creating pockets of variation even after national-level mergers. Canadian provincial regulators apply comparable oversight, preserving limited diversity in each-way offerings at seasonal tracks.
Studies from university-affiliated racing economics groups indicate that these regional differences produce measurable shifts in punter behavior. Volume migrates toward operators maintaining more generous place terms during key festival periods, while consolidated brands focus on volume through loyalty programs rather than term variation.
Future Outlook for Each-Way Products
Analysts project continued standardization through 2027 as remaining independent operators evaluate partnership or acquisition options. Regulatory filings suggest that any new consolidation deals will require review by multiple agencies across jurisdictions, potentially slowing the pace of change in each-way markets tied to seasonal fixtures.
Conclusion
Industry consolidations have produced measurable effects on each-way opportunities within seasonal racing calendars. Fewer pricing entities, aligned terms, and centralized risk management now characterize many major events scheduled through late 2026 and beyond. Data from competition authorities and racing associations document these structural shifts without indicating any reversal in the near term.